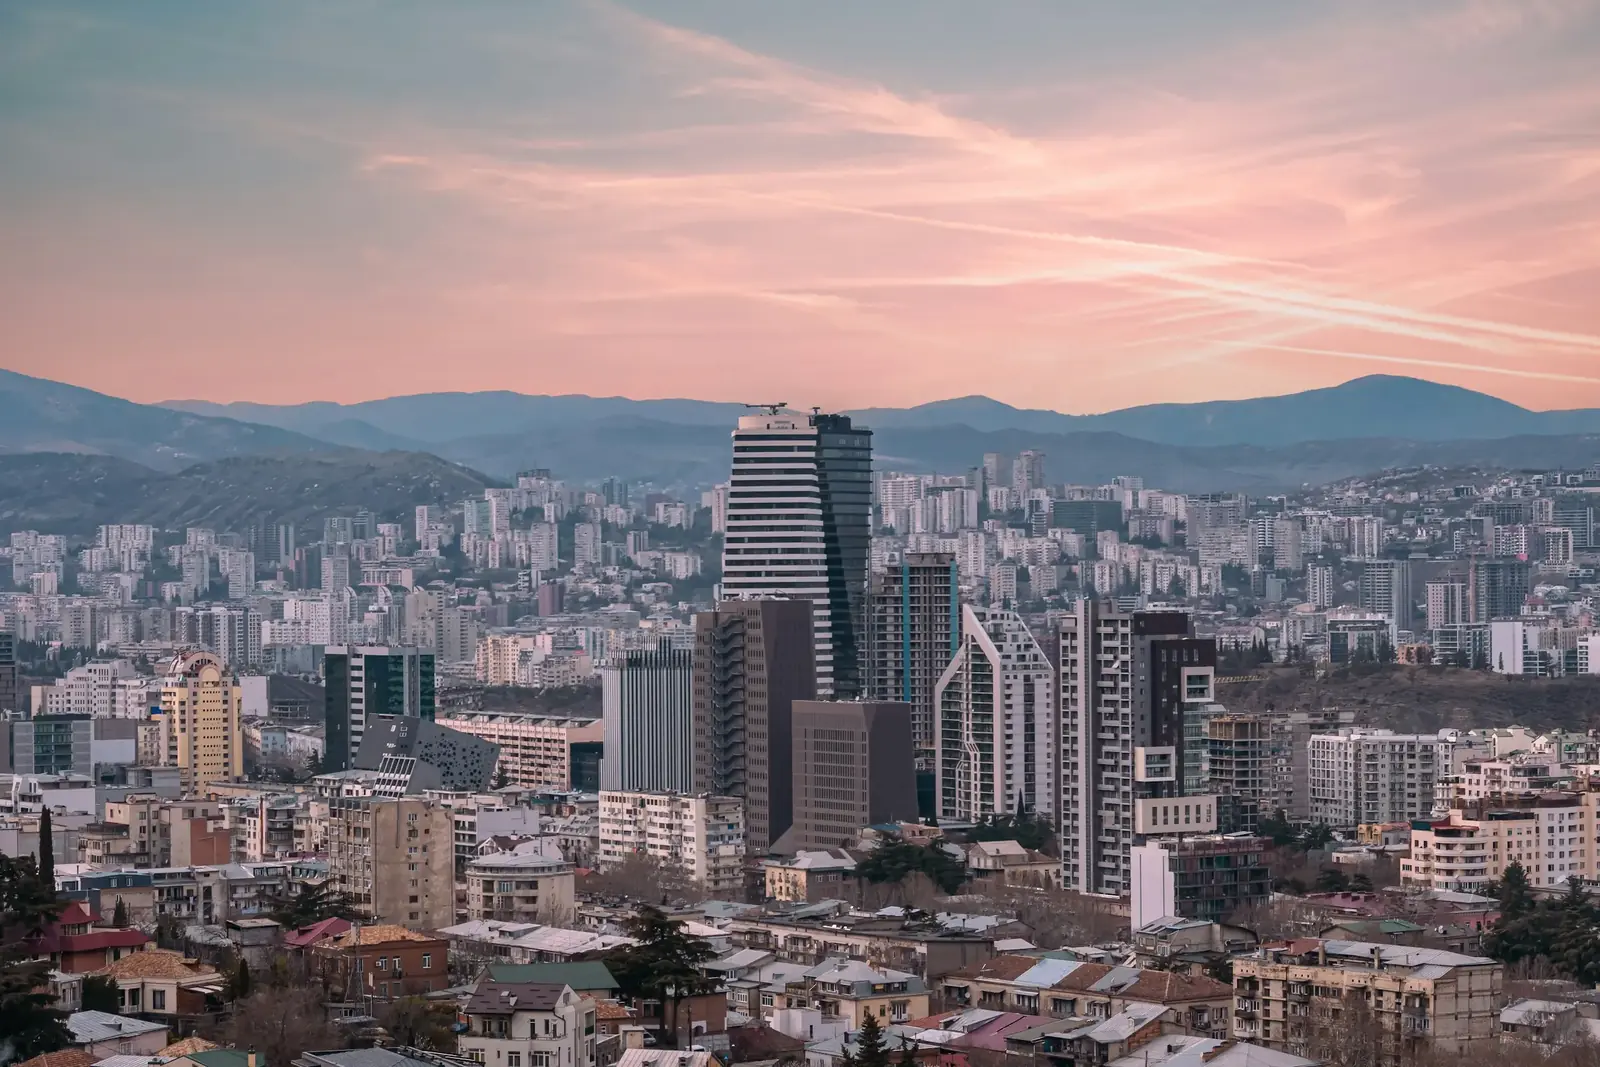
Georgia recorded approximately 78,500 residential property transactions in 2025. Tbilisi accounted for 42,388 apartment sales and Batumi for 17,478. Together, the two cities represented about 76% of the national total. That concentration can make them look like two locations within a single market.
They are not. Buying an apartment in Tbilisi and buying an apartment in Batumi usually solve different problems. Demand in the capital comes mainly from people who need a city for work, education, transport, healthcare and long-term housing. On the coast, investors and foreign buyers play a much larger role. They care about visitor demand, short-term rental performance, views, management and the ability to resell to another international buyer.
Price per square metre and advertised yield therefore make a poor starting point. The first questions are where the income will come from and who may want the apartment several years from now.
01 · Market depth and growth
A faster market is not necessarily a deeper one.
Tbilisi is substantially larger. Its 42,388 apartment sales in 2025 were 4.3% above the previous year, and the market was worth approximately US$3.57 billion. Batumi recorded 17,478 sales, up 15%, with a market value of about US$1.3 billion.
Batumi grew faster, but faster growth in a smaller market does not automatically mean greater liquidity. Tbilisi completed 2.4 times as many transactions. It has a wider buyer base, more long-term rental demand and less dependence on any single customer group.
The 2026 data preserves the distinction. Demand strengthened across both the primary and secondary markets in Tbilisi, where 27,274 transactions had been registered by the end of July. Batumi recorded 4,168 sales in the second quarter, 3.7% more than a year earlier. Secondary sales outpaced registered primary sales, although Galt & Taggart’s developer survey showed stronger current new-build demand. Registration delays explain part of that divergence and are a useful warning against reading any one indicator in isolation.
The indicators cover different reporting periods. Buyer nationality refers to samples of systematic developers, not the entire market. Rental yields are market estimates before the costs of an individual owner.
02 · Tbilisi
Tbilisi is bought for urban life.
Tbilisi’s main advantage is its own urban economy. Apartments are required by more than visitors and investors. Local employees, business owners, students, families and people moving from other parts of Georgia all create demand. That demand continues throughout the year and does not disappear when the tourist season ends.
Georgian citizens accounted for 77% of sales in Galt & Taggart’s survey of systematic developers in 2025. Foreign demand is relevant, but it supplements the market rather than defining it. For an investor, this reduces exposure to international marketing cycles, flight connectivity and the behaviour of buyers from one country.
The size of the city is not a guarantee of a good purchase. Tbilisi contains districts with very different price levels, density and audiences. Didi Dighomi led the city by sales volume in 2025, while Vake and Mtatsminda operated at much higher price points. A practical apartment near public transport and an expensive central property do not compete for the same tenant or buyer.
Long-term tenants care about transport, layout, heating, building condition and everyday services. A view may help, but rarely compensates for an inconvenient route or poor floor plan. At resale, the audience is usually broader than it is for a resort unit: the same apartment may appeal to an investor or an owner-occupier.
03 · Batumi
Batumi is bought as an operating product.
In Batumi, an apartment is more often presented as an investment product. Buyers assess the route to the sea, the view, the amenity package, the brand, the management company and expected income. Two neighbouring buildings can therefore produce very different results even when their prices per square metre look similar.
The market is much more exposed to foreign capital. Georgian citizens represented 33% of sales in Galt & Taggart’s sample of systematic developers during the first half of 2026. The figure does not describe all transactions in Batumi, but it is instructive for the new investment-led segment. International buyers expand the market, yet they also respond quickly to exchange rates, regional risk, residency rules and air connectivity.
Choosing Batumi, or even choosing a district, is not enough. The building must be assessed as a future operating business. How many similar units will be offered for rent? Who will manage them? What will the service charge cover? Can the owner use the apartment? How much remains after management commission, cleaning, utilities, vacancy and repairs?
Choose a project—not a market headline.
04 · Price
Price per square metre can mislead.
Average city prices are often placed side by side even when their definitions differ. Galt & Taggart reported a Tbilisi primary-market average of US$1,373 per square metre in December 2025 for white-frame apartments. Its Batumi figure was US$1,865 per square metre for completed primary-market units at the end of 2025 and US$1,960 in June 2026. The numbers are not directly comparable because one describes an unfinished interior and the other a completed product.
The gap between segments is more informative than the headline average. In June 2026, a completed primary-market apartment in Batumi cost about 31% more than an apartment in a relatively new building on the secondary market. Buyers were paying for more than floor area: the premium included a new brand, amenities, developer financing and expectations about future demand.
Internal instalment plans also became central to new-build sales in Tbilisi. They support demand but can obscure the cost of capital. The cash price and the total paid through a long instalment plan may be materially different. The relevant comparison is the final price, delivery risk and alternative use of the buyer’s capital, not simply the size of the deposit.
05 · Rental models
Rental income follows different models.
Tbilisi offers a relatively straightforward long-term rental model. Income is more evenly distributed through the year, expenses are easier to forecast and management does not depend on daily bookings. In December 2025, Galt & Taggart estimated rent for a typical 50–60 sq m apartment at US$9.8 per sq m and gross rental yield at 8.6%. The actual result still depends on district, condition, vacancy, tax and maintenance.
Batumi can generate stronger revenue during good months, but the annual result is shaped by seasonality. Estimated market yield was about 7.1% in June 2026, while average daily rates declined 4.2% during the quarter. Sales and prices were rising at the same time. A more expensive apartment was not necessarily becoming a more productive one.
A claim of 10–12% yield has little meaning without its assumptions. A serious calculation needs an achievable nightly rate, realistic occupancy, booking and management commissions, service charges, cleaning, utilities, tax, furniture replacement and a vacancy reserve. Two apartments with the same advertised gross yield can leave their owners with very different net income.
06 · New supply
New supply is becoming the main constraint.
Both cities are building heavily. In Tbilisi, permitted residential area declined to 1.734 million sq m in 2025 but remained above what Galt & Taggart describes as the healthy 2015–2022 range. Competition limits price growth and encourages developers to offer increasingly flexible instalments.
Batumi’s risk is more pronounced because the future pipeline is large relative to the size of the market. The developer sample contained approximately 12,400 unsold apartments at the end of 2025, 13.9% more than a year earlier. Much of the new stock is built around the same proposition: a compact apartment, short-term rental and an international investor.
An ordinary studio without a protected view, scarce layout or capable operator may therefore join a large pool of interchangeable units. At resale, the owner will compete with other investors and with developers offering new interiors and long payment plans.
07 · Exit liquidity
Liquidity is tested at exit.
Citywide transaction volume is only a rough measure of liquidity. The practical question is how many buyers may want the individual apartment.
A good Tbilisi unit can be sold to a local owner-occupier, a long-term rental investor or an international buyer. A recognisable district, transport access, an efficient plan and disciplined pricing matter most. The trade-off is slower growth in mature segments and substantial competition from new supply.
Batumi has access to a broader international audience, but the property itself faces a higher burden of proof. View, floor, building condition, actual management performance and a documented income history will matter at resale. Marketing promises lose their force once the building is complete and buyers can compare it with dozens of alternatives.
08 · Choosing the city
Start with five questions.
Who is the tenant? Who may buy the apartment at exit? What income remains after costs? How many direct competitors will exist by completion? What feature of this unit will be difficult to replicate?
The BUC view
Choose the source of demand first.
Tbilisi generally suits an investor seeking a deep urban market, long-term rent and a broad resale audience. Batumi suits an investor who understands seasonality, is prepared to assess the operator and can distinguish a scarce property from another studio in a large pipeline.
Both markets can produce a sound investment. Problems begin when a Tbilisi home is evaluated like a resort room, or a Batumi apartment like ordinary urban housing.
Choose the source of demand and the exit strategy first. The suitable city and property will follow from that decision.
BUC compares districts, developments and individual apartments on entry price, payment terms, operating costs, competition and a credible resale scenario.
Data checked on 22 September 2026. General information only; not individual legal, tax or investment advice.